GlensFalls.com logo
GlensFalls.com logo
  • Back to GlensFalls.com
  • Lodging
  • Restaurants
  • Things To Do
  • Events
Glens Falls Business Journal
  • Home
  • New Businesses
  • Business News
  • Business Reports
  • Business Briefs
  • Business Registrations
  • Personnel Briefs
  • Contact Us
Home  »  Business News  »  Coordinating Tax And Wealth Management Strategies Can Strengthen Year-End Planning
Business News

Coordinating Tax And Wealth Management Strategies Can Strengthen Year-End Planning

Posted onNovember 17, 2026
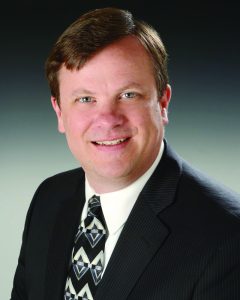
Kevin M. Hedley, MS, CPA, PFS, partner, Hedley & Co., PLLC.
Courtesy Hedley & Co. PLLC.

As 2026 ends, Capital Region business owners and families can make financial decisions affecting their tax bills and long-term security. Waiting until tax preparation could mean missing Dec. 31 deadlines.

An effective year-end review brings business cash flow, personal taxes, investments and retirement plans together. Coordinated tax and wealth management advice helps balance immediate needs against long-term goals.

Start by reviewing income. A strong business year, an unexpected bonus, investment gains or retirement withdrawals can substantially change a household’s tax bill. Reviewing withholding and estimated payments before year-end can reveal shortfalls in time to act. Meeting a tax payment safe harbor may prevent an underpayment penalty, but may not cover the balance due at filing.

For business owners, review current financial statements, anticipated receipts, planned expenditures and cash needed for payroll and operations. A tax adviser can assess the timing of income and deductible expenses under the business’s accounting method, evaluate retirement-plan funding and estimate their effect on owners’ personal returns. Purchases should meet business needs and fit the budget; a deduction alone does not justify them.

Several 2026 provisions make updated tax projections valuable. Eligible taxpayers age 65 or older may qualify for an additional deduction of up to $6,000 per person, subject to income limits. Deductions for qualified tips, certain overtime compensation and eligible personal vehicle loan interest have separate eligibility requirements. Evaluate each provision rather than assuming eligibility.

New York taxpayers should review itemized deductions. For 2026, the federal state and local tax (SALT) deduction cap is generally $40,400, or $20,200 for married taxpayers filing separately, with reductions at higher incomes. The benefit varies by taxpayer. A tax adviser can compare deductions and differences between federal and state treatment.

Coordinate investment decisions, too. Investment losses may offset realized capital gains. If losses exceed gains, up to $3,000 can generally offset other annual income, with unused losses carried forward; the annual limit is $1,500 for married taxpayers filing separately. The $3,000 limit restricts offsets against other income, not capital gains.

Before harvesting losses, review purchases across accounts for potential wash sales, including automatic dividend reinvestments. Project taxes before selling appreciated investments. The 3.8% net investment income tax can apply when modified adjusted gross income exceeds $200,000 for single filers or $250,000 for married couples filing jointly. Financial and tax advisers can coordinate diversification, cash needs and transaction tax projections.

Retirement planning connects current choices with future income. For 2026, the employee contribution limit for most 401(k) plans is $24,500. Participants ages 50 and older may contribute an additional $8,000 in catch-up contributions, for a total of $32,500. If allowed by the plan, participants ages 60 through 63 may instead contribute a higher catch-up amount of $11,250, for a total of $35,750. Beginning in 2026, participants whose previous-year FICA wages from the employer sponsoring the plan exceeded $150,000 must make any catch-up contributions as Roth contributions. If the plan does not offer a Roth option, they cannot make catch-up contributions making payroll and plan rules critical.

A Roth conversion may help in a lower-income year, but weigh its benefits against the current tax cost. Although conversion income itself is not net investment income, it can raise income enough to subject other investment income to the 3.8% tax. It may also affect deductions and trigger income-related monthly adjustment amounts (IRMAA), increasing Medicare Part B and Part D premiums generally two years after the conversion. Tax and financial advisers can model conversion amounts across multiple years.

Retirees should confirm required minimum distributions are taken by the applicable deadline, generally Dec. 31, with special rules for first distributions and inherited accounts. Coordinate withdrawals with spending, charitable giving and withholding to avoid surprises.

Review charitable giving. Beginning in 2026, nonitemizers may deduct eligible cash gifts of up to $1,000, or $2,000 for married couples filing jointly. For itemizers, a new floor generally allows a charitable deduction only for contributions exceeding 0.5% of adjusted gross income, subject to other limitations. Bunching planned gifts into one year may increase the tax benefit. Tax and financial advisers can compare giving strategies with charitable goals and available assets.

Finally, review beneficiary designations, insurance coverage, education savings and flexible spending accounts. Marriage, divorce, death or a business transition can make a plan outdated. Beneficiary designations often govern how retirement and insurance assets pass, so they should be coordinated with estate documents and reviewed with legal counsel when appropriate.

End year-end meetings with clear actions, deadlines and responsibilities. Coordinating tax planning and wealth management helps local businesses and families make informed decisions, preserve cash and plan for the new year.

Before acting on any year-end strategy, readers should consult their professional tax, financial and legal advisers to evaluate their individual circumstances.

Hedley & Co. PLLC and HK Wealth Management Group offer coordinated CPA and wealth management services.

Previous Article New IRS Mileage Rates Highlight Importance Of Accurate Business Travel Recordkeeping
Next Article The Park Theater Sets Winter Lineup
Subscribe to Our Newsletter View the Latest Virtual Edition
 SUBSCRIBE TO OUR NEWS FEED

Categories

  • 50-Plus
  • Banking
  • Banking / Asset Managment
  • Building Trades
  • Business Briefs
  • Business News
  • Business Registrations
  • Business Reports
  • Commercial / Residential Real Estate
  • Construction
  • Construction Planning
  • Corporate Tax / Business Planning
  • Cyber/Tech
  • Development
  • Dining Guide
  • Economic Outlook 2017
  • Economic Outlook 2018
  • Economic Outlook 2019
  • Economic Outlook 2020
  • Economic Outlook 2022
  • Economic Outlook 2023
  • Economic Outlook 2024
  • Economic Outlook 2025
  • Economic Outlook 2026
  • Economical Development
  • Education / Training
  • Entrepreneurial Women
  • Entrepreneurs
  • Entrepreneurship
  • Environment / Development
  • Exclusives
  • Financial Planning / Investments
  • Fitness / Nutrition
  • Health / Community Services
  • Health & Fitness
  • Health & Wellness
  • Healthcare
  • Holiday Shopping Guide
  • Home / Energy
  • Home & Real Estate
  • Insurance / Employee Benefits
  • Insurance / Medical Services
  • Leadership Development
  • Legal / Accounting
  • Meet The Chef
  • My Turn
  • New Businesses
  • Non-Profits
  • Office / Computers / New Media
  • Office / HR / Employment
  • Office / New Media
  • Office / Tech / eCommerce
  • Office / Technology
  • Office / Work Place / Legal
  • Outlook 2016
  • Outlook 2021
  • Personnel Briefs
  • Retirement Planning
  • Senior Living / Retirement
  • Summer Construction
  • Uncategorized
  • Wellness
  • Women In Business
  • Workplace / Legal / Security
  • Year-End Tax Planning

Archives

  • November 2026
  • October 2026
  • September 2026
  • August 2026
  • July 2026
  • June 2026
  • May 2026
  • April 2026
  • March 2026
  • February 2026
  • January 2026
  • December 2025
  • November 2025
  • October 2025
  • September 2025
  • August 2025
  • July 2025
  • June 2025
  • May 2025
  • April 2025
  • March 2025
  • February 2025
  • January 2025
  • December 2024
  • November 2024
  • October 2024
  • September 2024
  • August 2024
  • July 2024
  • June 2024
  • May 2024
  • April 2024
  • March 2024
  • February 2024
  • January 2024
  • December 2023
  • November 2023
  • October 2023
  • September 2023
  • August 2023
  • July 2023
  • June 2023
  • May 2023
  • April 2023
  • March 2023
  • February 2023
  • January 2023
  • December 2022
  • November 2022
  • October 2022
  • September 2022
  • August 2022
  • July 2022
  • June 2022
  • May 2022
  • April 2022
  • March 2022
  • February 2022
  • January 2022
  • December 2021
  • November 2021
  • October 2021
  • September 2021
  • August 2021
  • July 2021
  • June 2021
  • May 2021
  • April 2021
  • March 2021
  • February 2021
  • January 2021
  • December 2020
  • November 2020
  • October 2020
  • September 2020
  • August 2020
  • July 2020
  • June 2020
  • May 2020
  • April 2020
  • March 2020
  • February 2020
  • January 2020
  • December 2019
  • November 2019
  • October 2019
  • September 2019
  • August 2019
  • July 2019
  • June 2019
  • May 2019
  • April 2019
  • March 2019
  • February 2019
  • January 2019
  • December 2018
  • November 2018
  • October 2018
  • September 2018
  • August 2018
  • July 2018
  • June 2018
  • May 2018
  • April 2018
  • March 2018
  • February 2018
  • January 2018
  • December 2017
  • November 2017
  • October 2017
  • September 2017
  • August 2017
  • July 2017
  • June 2017
  • May 2017
  • April 2017
  • March 2017
  • February 2017
  • January 2017
  • December 2016
  • November 2016
  • October 2016
  • September 2016
  • August 2016
  • July 2016
  • June 2016
  • May 2016
  • April 2016
  • March 2016
  • February 2016
  • January 2016
  • December 2015
  • November 2015
  • October 2015
  • September 2015
  • August 2015
  • July 2015
  • June 2015
  • May 2015
  • April 2015
  • March 2015
  • February 2015
  • January 2015
  • December 2014
  • November 2014
  • October 2014
  • September 2014
  • August 2014
  • July 2014
  • June 2014
  • May 2014
  • April 2014
  • March 2014
  • February 2014
  • January 2014
  • December 2013
  • November 2013
  • October 2013
  • September 2013
  • August 2013
  • July 2013
  • June 2013
  • May 2013
  • April 2013
  • March 2013
  • February 2013
  • January 2013
  • September 2012
  • August 2012
  • July 2012
  • June 2012
  • May 2012
  • April 2012
  • March 2012
  • February 2012
  • January 2012
  • November 2010
Mannix Marketing Logo
GlensFalls.com logo
  • Home
  • Lodging
  • Restaurants
  • Things To Do
  • Nightlife
  • Events
  • Health & Beauty
  • Real Estate
  • Businesses
  • About
  • Home & Garden
  • Guides
  • Blogs
  • Sweepstakes
  • Advertising
Official Guide to the Greater Glens Falls Region
Full-Service Internet Marketing: Search Engine Optimization, Website Design and Development by Mannix Marketing, Inc.
Mannix Marketing, Inc. is headquartered in Glens Falls, New York
GlensFalls.com All Rights Reserved © 2026
Disclaimer & Privacy Policy / Terms of Use / Copyright Policies
[uc-privacysettings]

We strive to insure accuracy on GlensFalls.com however accuracy cannot be guaranteed. Information is subject to change.
Please alert us if there is any inaccurate information here.

Having trouble using this site? Accessibility is our goal, please contact us with site improvements.